
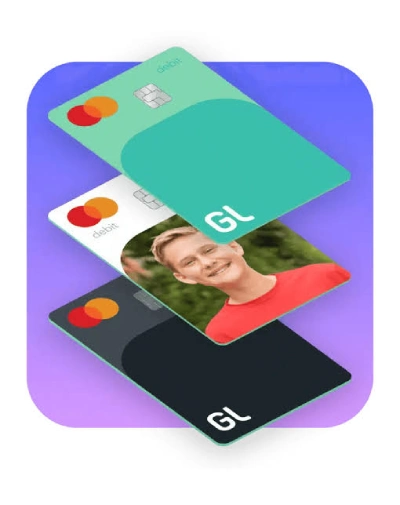
Greenlight’s most credible parent endorsement comes from FinanceBuzz’s reviewer who specifically used the card with her own children and found it “well worth the price for my family.” A Crafting With Kids mom reviewer frames the practical value simply: “Dividing cash out for my kids for allowance was always a pain since I rarely have much cash. I haven’t found a checking account that has all the perks of this card.” The most specific documented limitation: dozens of complaints on Reddit, Trustpilot, and the BBB report that parents struggled to resolve fraudulent charges or disputes — Greenlight couldn’t refund fraudulent charges and directed parents to talk to their own bank. For a product marketed as a family financial safety net, this dispute resolution gap is the most important buyer caveat.
Quick Highlights
✅ 6 million users — the most widely adopted kids financial platform in the US. Over 6 million people have used Greenlight as of January 2025. At this scale, the service’s infrastructure and reliability are documented across a genuinely large user base rather than a startup still proving its model.
✅ FDIC insured via Community Federal Savings Bank — SEC registered, FINRA and SIPC member. Greenlight partners with Community Federal Savings Bank for FDIC insurance and is registered with the SEC as Greenlight Investment Advisors, LLC. The regulatory framework is genuine — this is not an unregulated fintech operating without oversight.
✅ 2–5% savings reward for kids — real interest incentive on Savings balance. Children earn between 2% and 5% back on their Savings balance depending on the plan tier. This documented savings reward creates a concrete financial education moment — kids who save see real returns.
✅ Chore charts, spending controls, and real-time notifications — full parental oversight. Parents fund the card from their app, set per-store spending limits, receive real-time transaction alerts, and approve or block spending categories. Kids cannot spend money they don’t have. The parental control framework is the strongest available in the kids’ debit card category.
✅ Kids can invest in fractional shares — documented as a genuine learning tool. On the Max plan, kids can invest in fractional shares of real companies with parental approval. Financial Buzz documents this as a meaningful real-world financial literacy tool that no comparable kids’ card offers.
✅ Teenagers with jobs can set up direct deposit — practical for working teens. Teen cardholders with employment can route paychecks directly to their Greenlight account — making the platform a genuine bridge between a first job and independent financial management.
✅ Finder’s personal customer service test — representative was helpful and polite. Finder’s reviewer who personally contacted Greenlight support via text and phone documents a good experience resolving an issue with a helpful, polite representative. Direct personal testing of the service confirms the support can work well.
✅ BBB accredited since December 2017 — 3.8 out of 5 on Trustpilot from 5,500-plus reviews. The review volume and regulatory accreditation confirm Greenlight operates at legitimate institutional scale. Positive comments outweigh negative across the major platforms.
✅ Spend, Save, Give, Invest — four financial pillars taught through real money. The platform architecture teaches kids four fundamental money behaviours simultaneously — all with real money rather than simulated games. The learning is experiential rather than theoretical.
❌ Fraud disputes a documented nightmare — directed to own bank, not Greenlight. Dozens of Reddit, Trustpilot, and BBB complaints document parents struggling to resolve fraudulent charges. Greenlight’s response — directing parents to contact their own bank rather than resolving through Greenlight — reflects the platform’s prepaid card structure, where dispute rights differ from a traditional bank account. For parents who expect bank-level fraud protection, this structural limitation is a documented disappointment.
❌ Card declined at gas stations — pre-authorisation system incompatible. A ConsumerAffairs parent whose disabled son could never successfully use the card at gas stations documents the pre-authorisation issue: gas stations request a pre-authorisation amount that exceeds available balance, causing the card to decline even when the actual purchase amount is available. Greenlight’s workaround — add money and put it “on hold” — is documented as confusing and impractical for everyday use.
❌ Unauthorized charges reported — “every time we turned around there was some weird charge.” A ConsumerAffairs parent whose children used Greenlight for two years documents mysterious repeated charges appearing on the account. ConsumerAffairs reviews include “Do not use. They take money from your account without authorization” from a verified buyer. The pattern of unexpected charges is documented across multiple independent accounts.
❌ Monthly fee is unavoidable — $5.99 to $14.98 per month depending on plan. There is no free Greenlight tier. The monthly fee ranges from $5.99 for the Core plan to $14.98 for the Max plan. For parents who want a free checking account for kids, Greenlight’s mandatory subscription cost is a documented barrier — free alternatives like Chase First Banking or Capital One MONEY Teen exist, though without Greenlight’s feature depth.
❌ Non-refundable fees even if card never works — documented by disabled son’s parent. A ConsumerAffairs parent whose son with disabilities could never successfully use the card was told the fees were non-refundable despite the card being functionally useless for his needs. Non-refundable subscription fees on a non-functional product is a documented service failure.
❌ No physical branches — fintech limitation means no in-person support. Greenlight has no physical branches. All support is app, text, and phone based. For parents who prefer walking into a branch to resolve account issues — Greenlight structurally cannot provide this.
Why Trust This Review
This review draws on Finder’s independent Greenlight review including personal customer service test, FinanceBuzz’s family use editorial review, Young and the Invested’s feature analysis, Crafting With Kids mom reviewer personal experience, ConsumerAffairs verified parent accounts, and Trustpilot’s 5,500-plus review aggregate. No affiliate relationship with Greenlight exists.
Full Review Breakdown
The Financial Education Value — The Genuine Strength
Greenlight’s core proposition is financial education through real money — not an allowance app, not a spending tracker, but a system that teaches kids to earn, save, give, and invest simultaneously with their own real money under parental oversight. The chore chart that pays real money into a real card, the 2–5% savings reward that accumulates visibly, and the fractional share investing on the Max plan are the documented features that make Greenlight genuinely distinct from a basic teen checking account. Parents who use it consistently for 12-plus months with engaged kids document meaningful financial literacy outcomes — kids who understand savings interest, budget their spending, and make deliberate giving decisions.
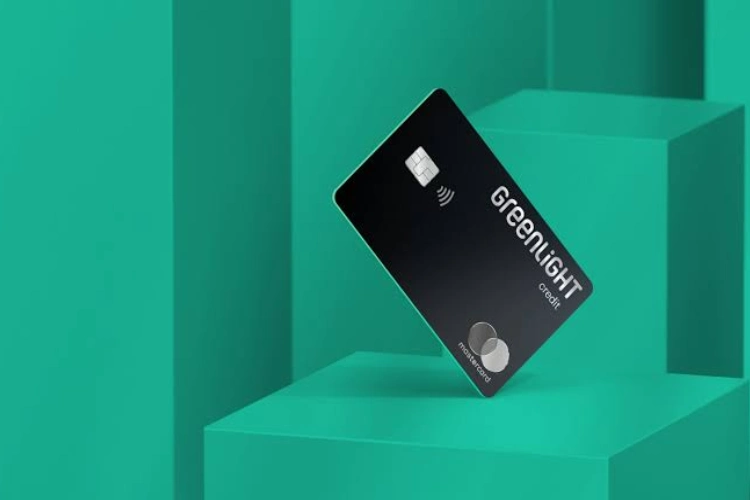
The Dispute and Fraud Gap — The Critical Limitation
Greenlight operates as a prepaid card, not a traditional bank account. This structural difference has important consumer protection implications: under the prepaid card framework, dispute resolution for fraudulent charges is handled differently than at a traditional bank. Greenlight’s documented response — directing parents to their own funding bank rather than resolving through Greenlight — is technically consistent with prepaid card regulations but creates a confusing accountability gap for parents who assumed bank-level fraud protection. Before signing up, understand: if a fraudulent charge appears on your child’s card, the resolution path runs through your own bank, not Greenlight’s support team.
The Gas Station Problem
Gas stations pre-authorise a hold amount — typically $75–$100 — before processing the actual fuel amount. For prepaid cards with limited balances, this pre-authorisation exceeds the available balance and triggers a decline even when the actual purchase amount would be covered. This is a documented structural incompatibility between prepaid cards and pay-at-pump fuel purchases that affects multiple prepaid cards beyond Greenlight. If your child regularly needs to use their card at gas stations, this documented issue is a practical daily-use problem.
Who Gets Maximum Value
The FinanceBuzz reviewer’s summary captures the right buyer profile: a parent who actively uses the app alongside their child, uses chore charts to create earning opportunities, discusses savings rewards with their kid, and uses the platform as a teaching tool rather than a set-and-forget allowance system. Greenlight delivers maximum value when parents are engaged with the educational features. Parents who primarily want a convenient way to transfer allowance money without teaching will find the monthly fee hard to justify against free alternatives.
Greenlight Plans and Pricing
Core — $5.99/month
Up to 5 kids, debit card, parental controls, chore charts, savings goals, 2% savings reward. Best for families who want the basic financial education toolkit without investment features.
Max — $9.98/month
Adds investing in real stocks and ETFs, 5% savings reward, Greenlight Black card, and market data. Best for families with older teens who are ready for real investment education.
Infinity — $14.98/month
Adds identity theft protection for the whole family, priority customer service, and additional safety features. Best for families who want comprehensive family financial protection alongside the kids’ card.
What Parents Actually Think
“The Greenlight debit card for kids was well worth the price for my family. As a parent, I was able to load the prepaid card using the Greenlight app, and my kids could access the funds.” — FinanceBuzz parent reviewer
“Dividing cash out for my kids for allowance was always a pain since I rarely have much cash anyways. I haven’t found a checking account that has all the perks of this card.” — Crafting With Kids mom reviewer
“I got this card for my son who has disabilities so that he always had available money for gas. He was never able to use the card as it was declined every time he attempted to use it. I was told their fees were not refundable even though the card was useless.” — ConsumerAffairs verified parent
“My kids were on this for a couple years and every time we turned around there was some weird charge. Do not sign your children up for this.” — ConsumerAffairs verified parent
“Having contacted Greenlight’s customer support via text and phone myself, I will mention I had a good experience resolving an issue and the representative was helpful and polite.” — Finder reviewer, personal test
Is Greenlight Worth It?
Best for: Engaged parents who want a structured financial education platform — not just allowance transfer — and will actively use chore charts, savings rewards discussions, and for older teens, the investing features. The 6 million user base and regulatory framework confirm this is a legitimate, stable platform.
Not ideal for: Parents whose children regularly pay at gas station pumps, families who expect bank-level fraud dispute protection, parents who want a free solution, and households where a parent won’t actively engage with the educational features.
Best alternative if cost is the barrier: Chase First Banking (free) or Capital One MONEY Teen (free) for basic spending control without the educational feature depth.
Greenlight vs Competitors
Feature | Greenlight Core | GoHenry | BusyKid | Chase First Banking | Capital One MONEY | Step |
Monthly Fee | $5.99 | $4.99 | $3.99 | Free | Free | Free |
Parental Controls | ✅ Best-in-class | ✅ Strong | ✅ Good | ✅ Good | ✅ Good | ✅ Good |
Chore Charts | ✅ | ✅ | ✅ | ❌ | ❌ | ❌ |
Kids Investing | ✅ Max plan | ❌ | ✅ | ❌ | ❌ | ✅ |
Savings Reward | ✅ 2–5% | ❌ | ✅ | ❌ | ❌ | ❌ |
FDIC Insured | ✅ | ✅ | ✅ | ✅ | ✅ | ✅ |
Gas Station Compatibility | ❌ Documented issue | ⚠️ Some | ⚠️ Some | ✅ | ✅ | ✅ |
Fraud Dispute Resolution | ⚠️ Via own bank | ⚠️ | ✅ | ✅ Better | ✅ Better | ✅ Better |
FAQs
Is Greenlight card safe for kids?
Yes — FDIC insured via Community Federal Savings Bank, SEC registered, and with real-time parental transaction alerts. The safety limitation is fraud dispute resolution, which routes through the parent’s own funding bank rather than Greenlight directly.
What is Greenlight's monthly fee?
$5.99 (Core), $9.98 (Max), or $14.98 (Infinity) per month. No free tier. For families who want similar basic features for free — Chase First Banking and Capital One MONEY Teen are alternatives without the educational feature depth.
Can Greenlight refund fraudulent charges?
Not directly — documented complaints show Greenlight directs parents to their own bank to dispute fraudulent charges. This is a structural prepaid card limitation, not a Greenlight-specific policy failure, but it creates a practical accountability gap.
Does Greenlight teach kids about money?
Yes — the chore chart, savings reward, Give feature, and investing tools are documented as genuine financial literacy mechanisms when parents use them actively alongside their children.
Greenlight vs GoHenry — which is better?
Greenlight for more comprehensive financial education features (investing, higher savings rewards, more parental controls). GoHenry for a slightly lower monthly fee and simpler interface. Both are legitimate kids’ financial platforms — the right choice depends on how many educational features the family will actively use.
Final Verdict
Greenlight is the most feature-complete kids’ financial education platform available — the chore charts, savings rewards, investing features, and parental control depth are documented as genuinely distinct from both free alternatives and simpler competitors. The 6 million user base, FDIC insurance, and SEC registration confirm institutional legitimacy. The honest limitations are specific: fraud disputes route through your own bank rather than Greenlight, gas station pre-authorisations create documented decline issues, and the mandatory monthly fee requires deliberate justification against free alternatives. For engaged parents who will actively use the educational features with their children — Greenlight is the most defensible investment in kids’ financial literacy available. For parents who want a basic spend-control card without educational engagement — a free alternative serves the need without the subscription cost.
Category | Score |
Financial Education Features | 9.5 / 10 |
Parental Control Depth | 9.5 / 10 |
Kids Investing (Max Plan) | 9.0 / 10 |
Fraud Dispute Resolution | 5.0 / 10 |
Gas Station Compatibility | 4.5 / 10 |
Monthly Fee Value | 7.0 / 10 |
Customer Service | 7.5 / 10 |
Regulatory Safety | 9.0 / 10 |
Overall | 7.6 / 10 |